Retail's recovery gained momentum in Q3 2026, with spending on physical goods increasing 4.6% year-on-year. Online shopping continued to lead the recovery, growing 10.7% compared with Q3 2025. While eCommerce accounted for just 22.4% of total retail spending, it generated almost half of the quarter's total retail growth, reinforcing its role as the primary driver of retail recovery heading into Peak 2026.
The stronger performance across both online and instore channels suggests consumer confidence is gradually returning. While inflation, fuel costs and election uncertainty remain factors to watch, retailers enter Peak with more momentum than they have seen in recent years.
Q3 2026 summary takeaways (compared to Q3 2025)
- Online spending grew 10.7%, more than three times faster than instore spending.
- Transactions and basket size both contributed to online growth, with transactions up 6.7% and average basket size up 3.7%.
- Online’s share of retail spending increased to 22.4%, up from 21.2% a year earlier.
- Domestic retailers strengthened their lead, capturing 79% of online spending.
- Discretionary categories led online growth, particularly homeware, appliances, electronics, recreation and books.
- Year-to-date online spending is up 11.4% heading into Peak.
The numbers behind the growth
Online spending reached $3.14 billion in Q3 2026, up 10.7% from Q3 2025. This was significantly ahead of the 2.9% growth recorded instore, reinforcing eCommerce’s position as the primary engine of retail growth.
In recent years, much of online’s momentum has come from shoppers making more frequent purchases while keeping a close eye on how much they spend each time. In Q3 2026, transactions continued to grow strongly but were also supported by a larger average spend (basket size). The average online basket increased by 3.7% to $122, more than double the average instore basket of $54. This suggests growing confidence in making considered, higher-value purchases online.
Q3 2026 online snapshot (growth vs Q3 2025)
Spending $ 3.14b+10.7% | Transactions 25.6m+6.7% | Average basket size $122+3.7% |
Q3 2026 instore snapshot (growth vs Q3 2025)
Spending $10.87b+2.9% | Transactions 200.5m+2.0% | Average basket size $54+0.9% |
Instore recorded a stronger result than in recent quarters, driven by small gains in both transaction volumes and basket size. And while instore growth is a good sign for the retail sector overall, this growth remains modest and below the rate of inflation1.
Together, these results suggest the retail recovery is broadening across both online and physical channels.
HELPFUL HINT FROM NZ POST
Turn growing confidence into Peak momentum. Re-engage existing customers early by reminding them of your story, what makes your offer unique and what other shoppers say about you. Preview upcoming Peak offers and key dates across email and social channels to build excitement and give loyal customers a reason to include you in their planning for the upcoming ‘big sales’ season.
Domestic retailers extend their dominance
The strongest shift in Q3 wasn't just growth in online spending, but where that growth came from. After several years in which international retailers benefited from increasing transaction volumes, growth was overwhelmingly driven by domestic retailers this quarter.
Online spending with local retailers grew by 12.3% from the year before. As a result, nearly 80% of all online spending in the last quarter was with local retailers.
Q3 2026 Domestic vs International (growth vs Q3 2025)
Spending with of $2.47b+12.3% | Spending with of $0.66m+4.9% | Domestic share of 79%Up from 77.8% |
Local transactions for the quarter grew by 9%, while international transactions grew by less than 2%. Average basket sizes increased by around 3% for both domestic and offshore retailers. However, the value of a local online purchases remained substantially higher with the average domestic basket at $139, compared to $85 for offshore.
Kiwi shoppers actively choose to buy locally to support the local economy, for faster delivery, easier returns and the reassurance that comes from dealing with a retailer they know and trust. This local advantage will become even more valuable during Peak, when shoppers need confidence that purchases will arrive on time.
HELPFUL HINT FROM NZ POST
Make your local advantage visible. Clearly communicate where stock is held, when customers can expect delivery and how returns work. Trusted fulfilment, proactive tracking and accessible local support can provide the reassurance shoppers need, especially as Christmas gets closer. Find out more about the importance of trust, transparency and buying local in our Market Sentiments 2026 Report.
Discretionary sectors lead the way
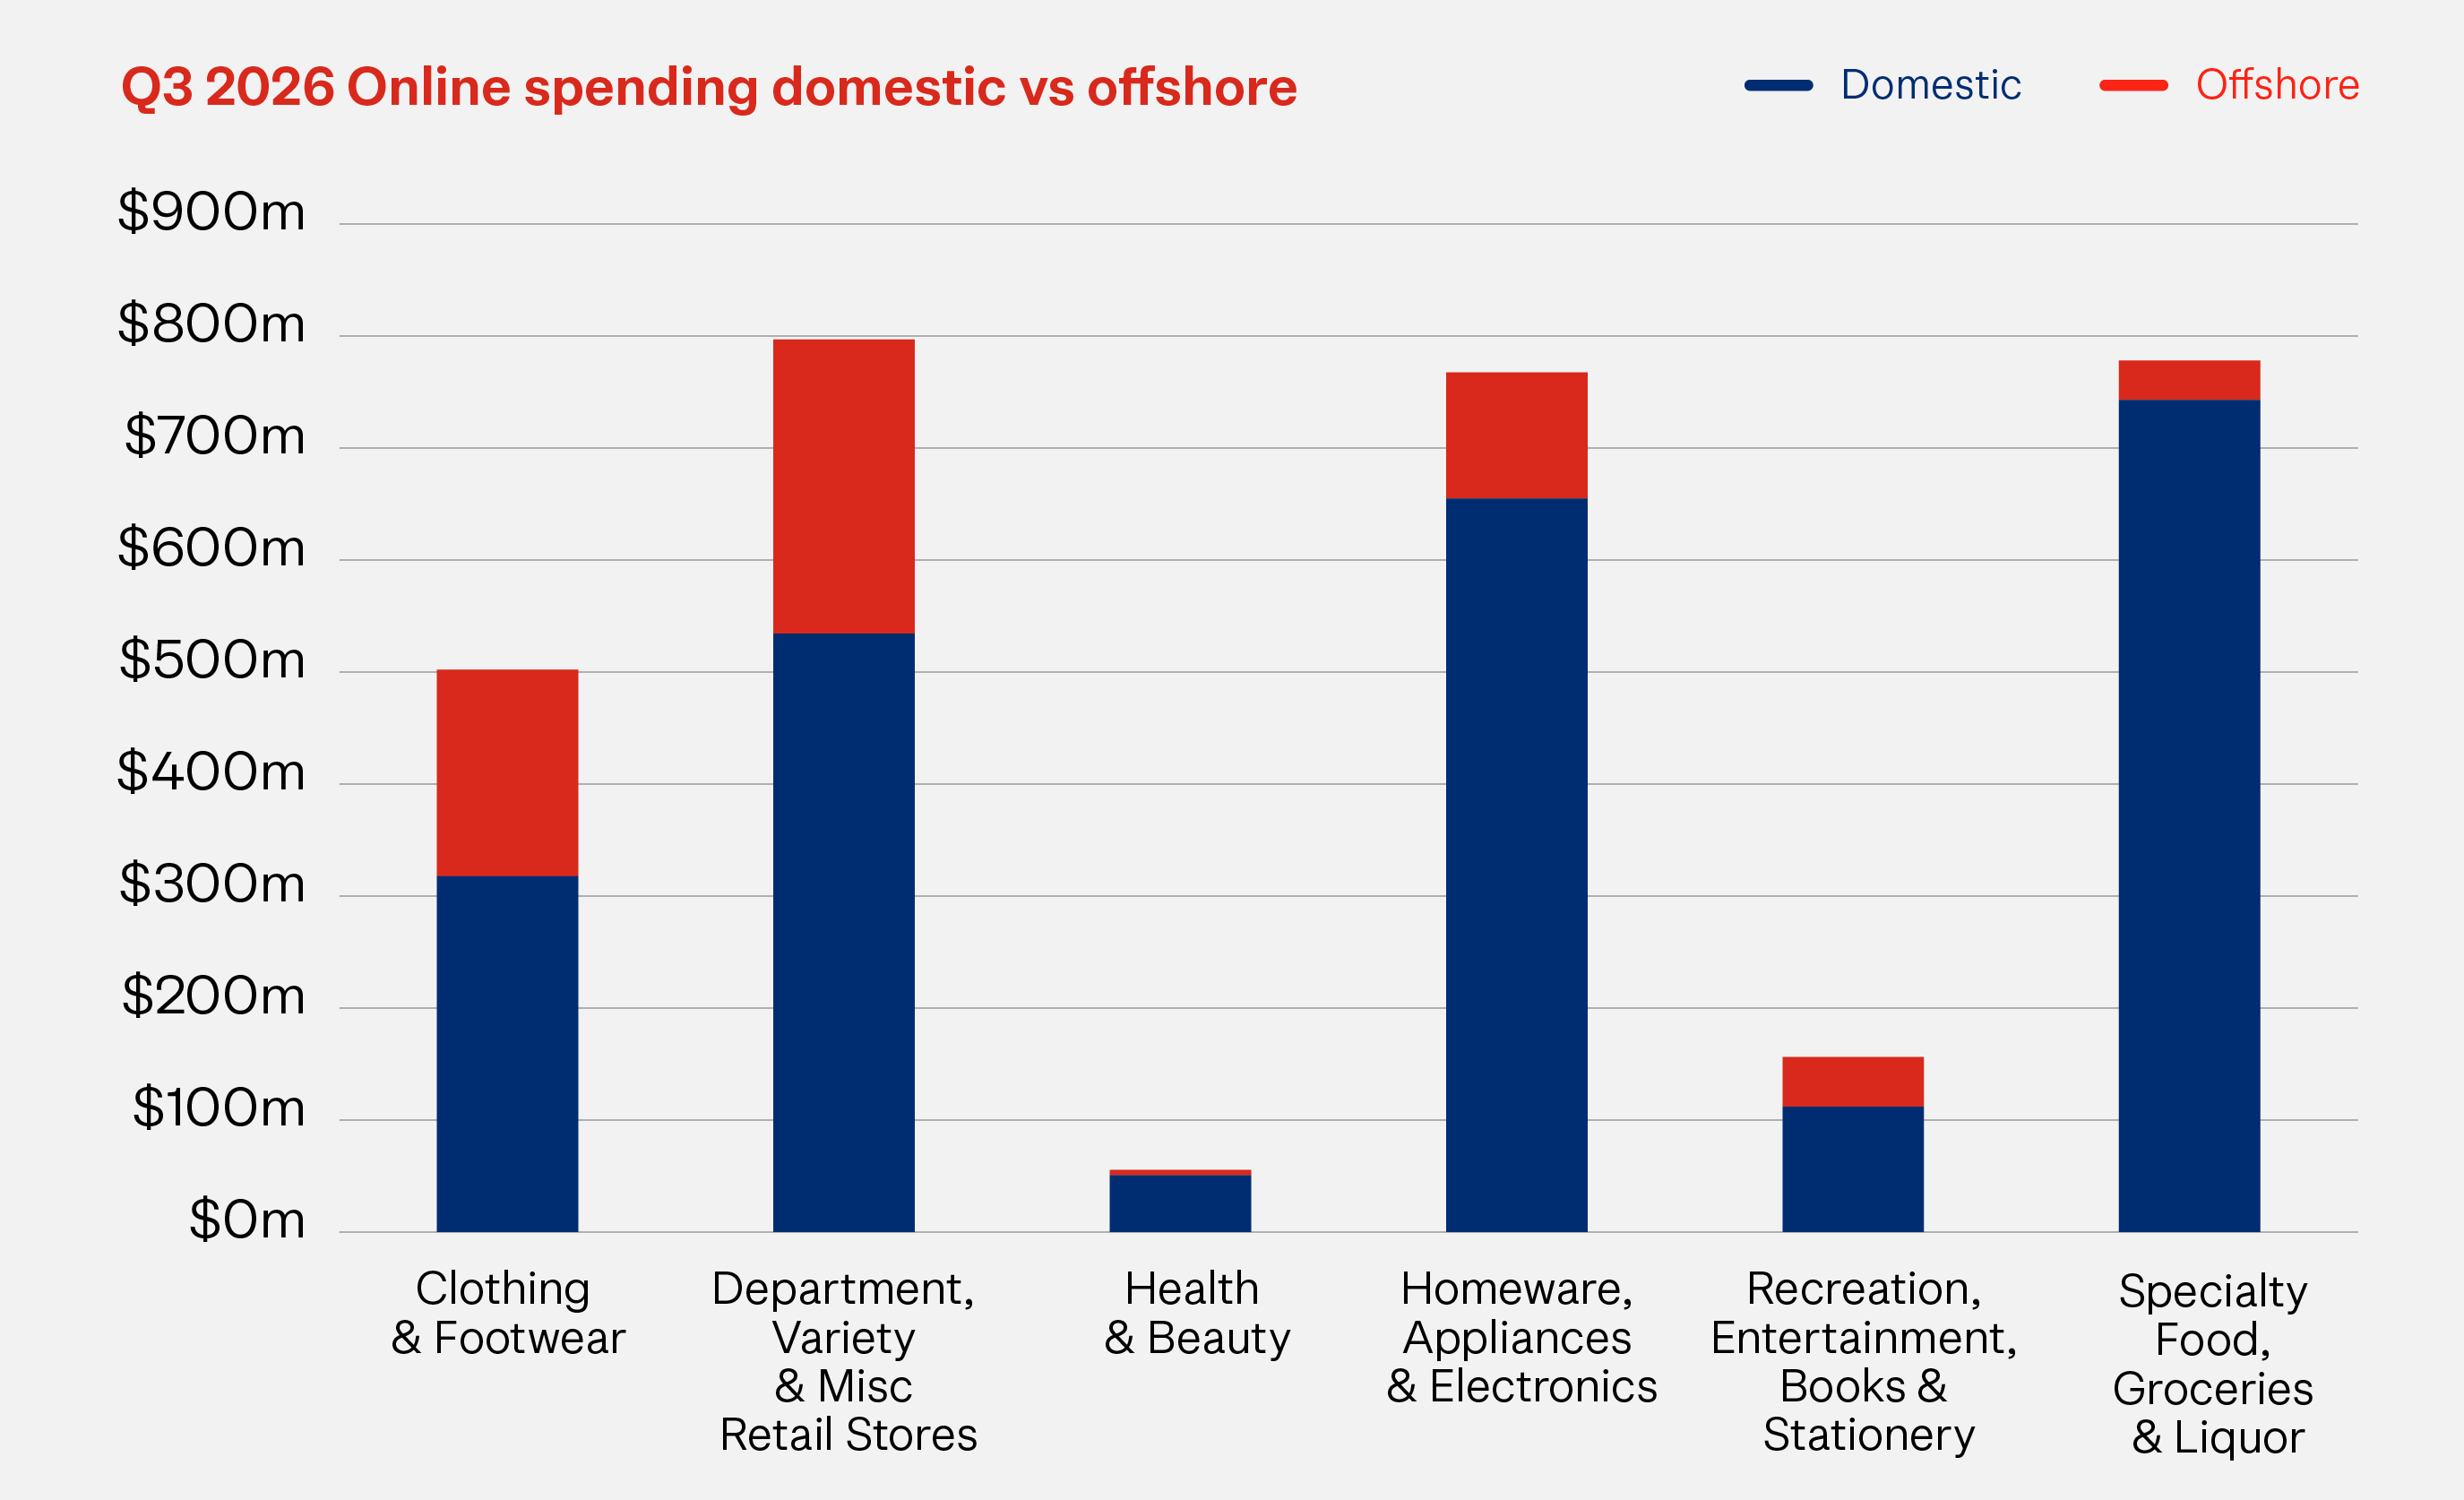
Q3 2026 saw strengthening demand beyond everyday essentials. Online spending increased in five of the six major sectors, led by Homeware, Appliances & Electronics and Recreation, Entertainment, Books & Stationery. Most categories grew through a combination of transaction and basket growth, though Department, Variety & Miscellaneous Retail grew entirely through larger baskets. Health & Beauty was the only major sector to record an online decline, contrasting sharply with strong growth instore.
Growth was led by discretionary categories, suggesting consumers are increasingly comfortable spending beyond everyday essentials. Homeware, Appliances & Electronics and Recreation, Entertainment, Books & Stationery delivered the strongest gains, while Health & Beauty was the only sector to decline online despite strong instore growth.
Q3 2026 vs Q3 2025 Homeware, Appliances & Electronics (24% online market share)
Spending growth +17%
| Transaction growth +20%
| Basket size $161-2% |
- Domestic online spending +17%; International online spending +19%
- Instore spending +4%
Q3 2026 vs Q3 2025 Recreation, Entertainment, Books & Stationery (5% online market share)
Spending growth +17%
| Transaction growth +16%
| Basket size $130+1% |
- Domestic online spending +19%; International online spending +10%
- Instore spending +7%
Q3 2026 vs Q3 2025 Specialty, Food & Liquor (25% online market share)
Spending growth +11%
| Transaction growth +10%
| Basket size $133+1% |
- Domestic online spending +12%; International online spending -2%
- Instore spending +2%
Q3 2026 vs Q3 2025 Clothing & Footwear (16% online market share)
Spending growth +10%
| Transaction growth +9%
| Basket size $127+1% |
- Domestic online spending +8%; International online spending +14%
- Instore spending +5%
Q3 2026 vs Q3 2025 Department, Variety & Misc. Retail (25% online market share)
Spending growth +5%
| Transaction growth -2%
| Basket size $92+8% |
- Domestic online spending +12%; International online spending -5%
- Instore spending +2%
Q3 2026 vs Q3 2025 Health & Beauty (2% online market share)
Spending growth -2%
| Transaction growth -8%
| Basket size $114+7% |
- Domestic online spending -3%; International online spending +9%
- Instore spending +14%
HELPFUL HINT FROM NZ POST
Respond to your category’s growth pattern. Higher transaction volumes create opportunities to build frequency and loyalty, while larger baskets support bundling and threshold-based delivery offers. As the Market Sentiments 2026 Report highlights, value means more than discounting: quality, trust, reliability, local relevance and an easy customer experience can all influence where shoppers buy.
Year to date: Online remains the growth engine
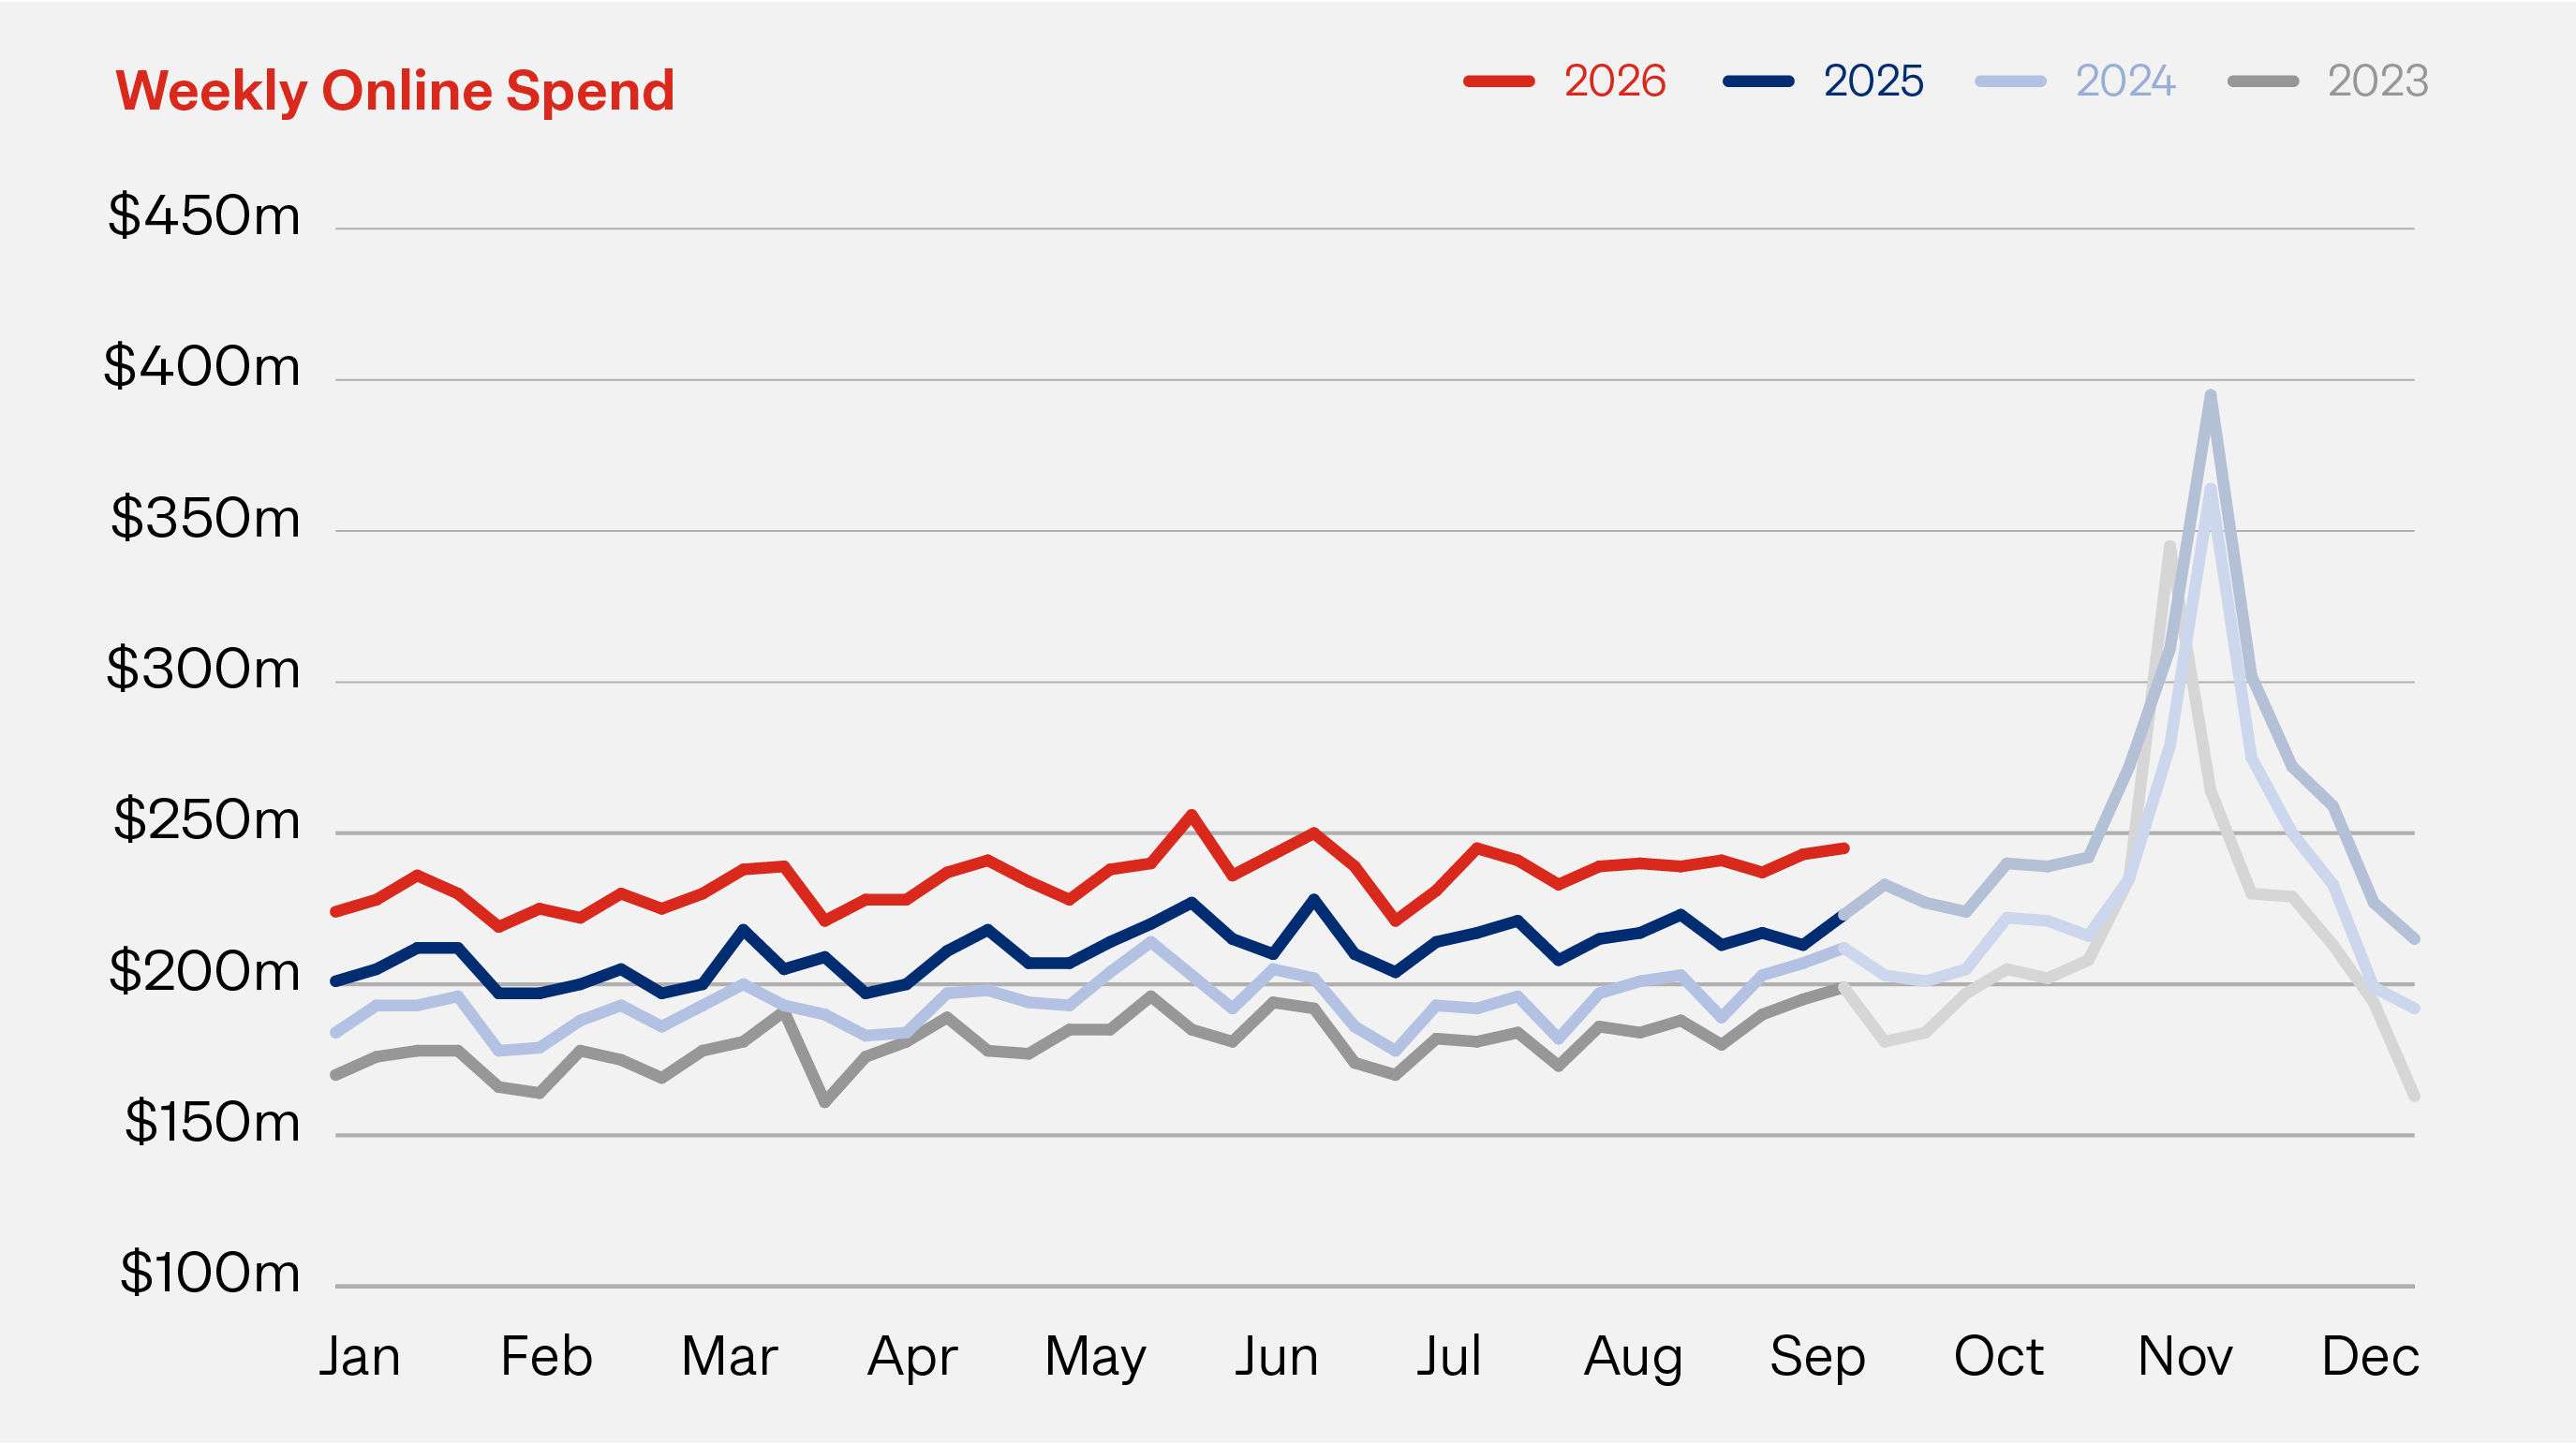
This quarter’s numbers build on the momentum seen through the first half of 2026. Online spending has maintained double-digit growth across the year, while domestic retailers have consistently outperformed their offshore competitors.
Online spending reached $9.15 billion, an increase of 11.4%, compared with 2.5% growth instore. Domestic online retailers again lead the way, with increased spend of 12.5%, while offshore spending grew by 7.6%.
Looking ahead: Momentum meets uncertainty
Retailers head into Peak with considerably more momentum than they had a year ago. Double-digit online growth, shoppers choosing local purchases, improving instore performance and stronger discretionary spending all point to growing confidence among Kiwi shoppers. The retail sector enters this Peak period from a much stronger position than it did in 2025.
The wider economic environment, however, continues to moderate this momentum. GDP increased by a modest 0.2% in the June quarter, lifting annual growth to 1.7%2. Residential construction, wholesale trade and manufacturing moved positively but conditions were softer in other sectors, suggesting a recovery that is gradual and uneven. Higher global oil prices and a weaker New Zealand Dollar have increased costs for households and businesses. Economic forecasters generally expect inflationary pressure to remain elevated to the end of the year. And the election adds another layer of uncertainty. Some shoppers may defer major purchases, while businesses may delay investment decisions until the composition and priorities of the next government become clearer.
Retailers cannot control the election result, interest rates, fuel costs or global events. They can, however, control how prepared they are to respond. In the quarter ahead, we encourage retailers to focus on:
- Prepare for demand but retain flexibility. Secure key inventory, confirm fulfilment capacity and test your digital systems early. Keep stock, pricing and marketing plans flexible so you can respond quickly as demand develops.
- Deliver value beyond discounts. Use quality, bundles, loyalty benefits, delivery certainty and easy returns to offer value while protecting margins.
- Make trust and transparency visible. Clearly communicate contact details, returns policies, delivery costs and Christmas cut-offs. Realistic timeframes and proactive tracking give shoppers’ confidence during Peak.
- Create an excellent web-to-door experience. Remove friction from discovery and checkout through to delivery and returns. Flexible options and clear updates can turn Peak purchases into repeat business.
- Play to the local advantage. Highlight faster delivery, easy returns, accessible service and your connection to local communities. These local strengths can be more compelling than competing on price alone.
For more insights and tools to help you get ready for Peak 2026, visit our Peak Hub.
About our new data methodology. We're continuing to review and evolve our data methodology to ensure we deliver the most complete picture of New Zealand's online shopping landscape. This edition of eSpotlight features a new approach using a variety of credible sources, moving beyond our previous reliance solely on card transaction data. Data was compiled and provided by leading data analysis firm, Dot Loves Data.
As online shopping has evolved, we've expanded our data collection to include payments made through mobile apps, digital wallets, and other payment platforms that better reflect how Kiwi shoppers purchase today. To maintain accuracy in our comparisons, this new methodology has been applied retrospectively to previous periods, ensuring all information is presented on a like-for-like basis.
We've also extended our analysis to provide more detailed sector category data, delivering more granular insights for retailers. As the eCommerce environment continues to evolve, we remain committed to refining our approach to capture the full spectrum of online shopping activity and deliver the most valuable insights for New Zealand retailers.
This report is published for general information purposes only. The views and opinions expressed, and any advice provided, is general in nature only. NZ Post does not represent that any information or advice it contains is suitable for your circumstances or purposes.
2 https://www.stats.govt.nz/indicators/gross-domestic-product-gdp/